The Tax Department issued Official Letter No. 6482/CT-QLNT dated August 28, 2026, responding to the Association of Foreign-Invested Enterprises regarding tax policy on labor leasing activities and payments to suppliers before the supplier ceases operations, abandons business premises, goes bankrupt, or commits legal violations. Regarding this group of expenses, the tax authorities stated that the consideration of deductible expenses when determining taxable corporate income must be based on the legal regulations of each period, actual records, invoices, receipts, and related documents.
What are the contents of Official Document 6482/CT-QLNT?
Official Letter 6482/CT-QLNT, issued by the Tax Department in Hanoi on August 28, 2026, was sent to the Association of Foreign Investment Enterprises. This document responds to the Association's Official Letter No. 111/HHDNĐTNN-HTDN regarding tax issues related to labor leasing and expenses for businesses ceasing operations. The content of the document is published here. Official document 6482/CT-QLNT on LuatVietnam..
The document comprises two main sections. The first addresses tax policies related to labor outsourcing; the second focuses on how to consider payments to suppliers before they cease operations, abandon their business premises, go bankrupt, or commit legal violations.
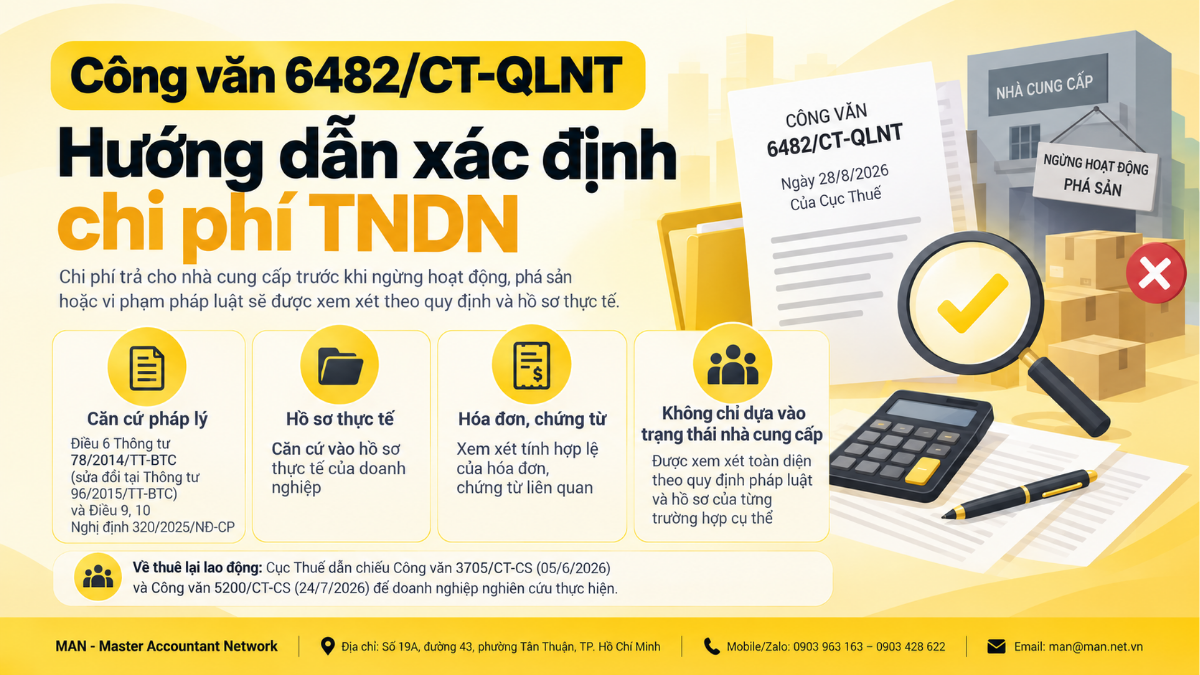
Regarding labor outsourcing activities, Circular 6482/CT-QLNT does not reiterate the entire policy but refers to two circulars previously issued by the Tax Department. Specifically:
- Official letter No. 3705/CT-CS dated June 5, 2026, in response to the Phu Tho Provincial Tax Department.
- Official letter No. 5200/CT-CS dated July 24, 2026, in response to the Korean Business Association in Vietnam.
The Tax Department stated that it is attaching copies of the two aforementioned official letters for the Association to review and disseminate to its member businesses for compliance with regulations.
Official document 6482/CT-QLNT provides guidance on determining deductible expenses.
A key focus of Circular 6482/CT-QLNT is payments made to suppliers before the supplier ceases operations, abandons its business location, goes bankrupt, or commits other legal violations. The Tax Department determined that the consideration of deductible or non-deductible expenses when determining taxable corporate income must be based on the legal grounds outlined in the circular.
According to the document, the cited basis includes Article 6 of Circular 78/2014/TT-BTC dated June 18, 2014, of the Ministry of Finance, as amended and supplemented by Circular 96/2015/TT-BTC, along with Articles 9 and 10 of Decree 320/2025/NĐ-CP dated December 15, 2025, of the Government. Businesses can directly verify this information. Circular 78/2014/TT-BTC on the Government's Electronic Information Portal and Decree 320/2025/ND-CP on the Government's Electronic Information Portal when reviewing the legal basis.
According to Official Letter 6482/CT-QLNT, when the above-mentioned case arises, the tax authority will consider the following main groups of information:
| Content under review | Interpretation according to the Official Document | The significance of reviewing records |
| Legal regulations in each period | Apply the tax regulations appropriate to the time the expense is incurred. | Determine the correct legal basis according to the tax period. |
| Actual records | Review the records to see the actual transactions and expenditures. | Verify the completeness and consistency of the documentation. |
| Invoices and receipts | Check the invoices and supporting documents related to the expenditure. | To serve as proof that the expense incurred is legitimate. |
| Related documents | Review other documents specific to each case. | This provides additional grounds for the tax authorities to assess eligibility for deductions. |
Supplier bankruptcy is not the only basis for disallowing expenses.
One point to note from Official Letter 6482/CT-QLNT is that the legal status of a supplier is not the sole basis for determining whether an expense is deductible or not. The Tax Department clarifies that the determination must be considered based on tax laws, actual records, invoices, receipts, and related documents for each specific case.
Therefore, it should not be assumed that all payments made to a supplier before the supplier ceases operations, abandons its business location, or goes bankrupt are automatically deductible expenses. Conversely, Circular 6482/CT-QLNT does not conclude that the buyer's payment is automatically disallowed simply because the supplier falls into one of these states.
The tax authority's approach is to assess based on specific records and circumstances. Businesses can refer to MAN's content for more information on this topic. Deductible expenses when calculating corporate income tax. To systematize the groups of conditions and records that are regularly reviewed.
What should businesses consider when reviewing supplier payment costs?
Based on the content of Official Letter 6482/CT-QLNT, businesses should focus on checking the completeness and verifiability of documents related to the expenditure. The tasks that need to be reviewed include:
- Determine when the expense was incurred and compare it with the applicable tax regulations for the corresponding period.
- Verify the actual records proving the transaction and the purpose of the expenditure.
- Review invoices, receipts, and other documents related to transactions with suppliers.
- Check the supplier's status, but do not use this status alone as the sole basis for concluding whether expenses are deductible.
For businesses dealing with suppliers who have ceased operations or are no longer operating at their registered address, the review should be considered within the overall tax records and transaction documentation. Further information regarding the cessation of operations can be found at [link/website]. Tax obligations when dissolving a business. and temporary suspension of operations on MAN's professional content platform.
Key information from Official Letter 6482/CT-QLNT
| Number | 6482/CT-QLNT |
| Issuing authority | Tax Department – Ministry of Finance |
| Abstract | Regarding tax policy |
| Date of issuance | 28/8/2026 |
| Recipient | Association of Foreign Investment Enterprises |
| Key content | Tax policy regarding labor leasing and payments to suppliers before the supplier ceases operations, abandons business premises, goes bankrupt, or commits legal violations. |
The official document is dated August 28, 2026. The Tax Department does not specify a particular effective date in the provided document; therefore, this article uses the phrase "date of issuance" instead of "effective date".
Conclude
Official document 6482/CT-QLNT indicates that determining whether payments to suppliers are deductible for corporate income tax purposes does not solely depend on the supplier's status. The tax authorities will consider each case based on applicable laws, actual records, invoices, receipts, and other relevant documents.
For businesses, the focus is not only on monitoring supplier activity but also on maintaining complete, consistent, and verifiable transaction records. For further information on costs associated with business closure, please refer to the relevant section. business dissolution costs and Bankruptcy Law 2014 on MAN's content system.
Main source: Official document No. 6482/CT-QLNT August 28, 2026, from the Tax Department. The content of this article follows the original document and content from Vietnam Law Provided; external links are for referencing legal texts and publication sources.
Professional license: CPA Vietnam Auditors
Experience: Over 30 years of experience in Accounting, Auditing, and Financial Consulting.