Business dissolution is a mandatory legal process when the owner no longer wishes to continue operating or the company is no longer eligible to do so. Understanding this process helps businesses legally withdraw from the market while avoiding unnecessary tax risks and administrative penalties. This article provides a detailed roadmap for completing the termination of a business's existence according to the provisions of the 2020 Enterprise Law and its implementing regulations.
Conditions for a business to be allowed to dissolve.
According to the provisions of Article 207 Enterprise Law 2020, In general, a business can only be dissolved when it fulfills its financial obligations. This is a legal barrier aimed at protecting the rights of all parties involved before the economic entity ceases to exist.
To carry out the business dissolution procedure, the entity must satisfy the following criteria:
- All debts and other financial obligations, including salary debts, tax debts, social insurance debts, and debts to business partners, have been settled.
- Not currently in the process of resolving a dispute in court or arbitration (in case of a dispute, the proceedings will be suspended until a final decision is reached).
- All financial reports have been prepared and tax settlement procedures have been completed with the directly supervising tax authority.
Common cases of business dissolution
The law recognizes two main forms of dissolution: voluntary (at the will of the owner) and compulsory (by decision of a state agency). Specific cases where business dissolution procedures apply include:
- The company's operating period, as stated in its charter, has expired without a decision to extend it from the contributing members or shareholders.
- Voluntary dissolution is carried out by resolution or decision of the private enterprise owner, the Board of Members (for limited liability companies), or the General Meeting of Shareholders (for joint-stock companies).
- Businesses that no longer have the minimum number of members required by law for a continuous period of 06 months without undergoing the procedure to change their business type.
- The business registration certificate has been revoked by the authorities due to violations of the law or by a court decision.
A detailed and in-depth guide to the business dissolution process.
To complete the business closure process, a company must go through two main stages: working with the tax authorities and working with the business registration authority. MAN – Master Accountant Network notes that the tax settlement stage is often the most complex, requiring transparency in accounting records to expedite the business dissolution process.
Through resolutions and decisions on dissolution.
The first step is to reach an internal consensus on ceasing operations.
- The company holds a meeting to pass a resolution on dissolution. The document must include information on the reasons for dissolution, the debt settlement plan, and the contract liquidation deadline (not exceeding 6 months).
- Within 7 working days from the date of approval, the enterprise must send a notice to the Business Registration Office, creditors, and employees to begin the formal dissolution procedures.
Fulfilling obligations at tax and customs authorities.
This stage determines whether the business has fulfilled its "financial obligations" to the state.
Complete the procedure for closing the tax identification number.
Businesses must submit an application to terminate their tax identification number in accordance with Circular 105/2020/TT-BTC. The tax authority will inspect the books and documents to confirm that the business no longer owes taxes and issue Notice Form 22-MST, which is the prerequisite for completing the business dissolution procedure.
Confirmation of obligations at the General Department of Customs
If the business is registered to operate in the import-export sector, it is mandatory to obtain a certificate confirming that it has no outstanding import-export tax debts. This step helps eliminate tax-related issues during the business dissolution process.
Cancel invoices and dissolve the branch.
If a business has subsidiaries such as branches or representative offices, these subsidiaries must complete the dissolution process before the parent company proceeds with the final step.
Submit the final dissolution documents at the Business Registration Office.
After receiving confirmation of tax code closure, the business prepares the necessary documents to submit to the business registration authority to remove its name from the national register.
- Application deadline: Within 5 working days from the date all debts are fully paid.
- The result: Within 5 working days from the date of receiving all valid documents, the Business Registration Department will update the business status on the system to "Dissolved," thus completing the business dissolution procedure.
Instructions for submitting business dissolution documents online
Currently, submitting applications online through the National Business Registration Portal has become common and mandatory in some major provinces and cities. The online application process for business dissolution includes the following steps:
- Register an account on the system and use a public digital signature to submit your declaration.
- Upload all scanned copies (PDF) of the documents, including the decision, meeting minutes, and asset liquidation report.
- Receive valid notification from the system and submit paper documents (if required by the local authorities) or receive electronic results as per regulations.
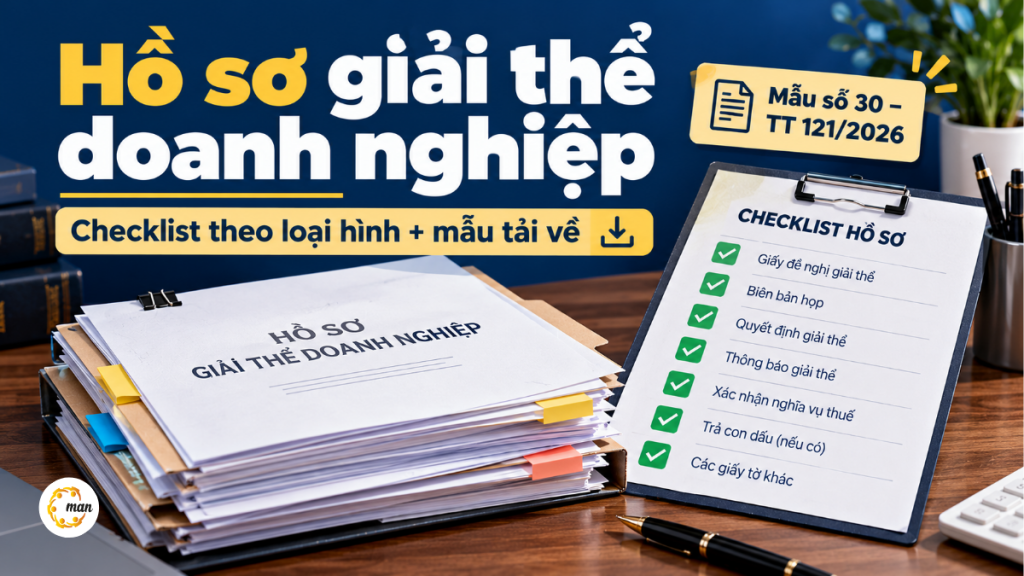
Documents required for business dissolution must be prepared according to regulations.
Thorough preparation of paperwork will help expedite the approval process. Below is a list of documents required for business dissolution, compiled by MAN – Master Accountant Network:
| Type of document | Quantity | Legal basis |
|---|---|---|
| Announcement of dissolution | 01 original copy | Appendix II-22 (Decree 01/2021) |
| Asset liquidation report | 01 original copy | Article 208 of the 2020 Enterprise Law |
| Resolutions and meeting minutes | 01 copy | Article 207 of the 2020 Enterprise Law |
| List of debts paid | 01 original copy | This includes tax debts, wages, and insurance contributions. |
Businesses should note that the asset liquidation report must include a plan for handling benefits arising from employment contracts to avoid lawsuits after the business dissolution process is completed.
Differentiate procedures for each type of company.
Depending on the type of ownership, the authority to sign and issue decisions regarding the dissolution of a business will differ significantly:
- Limited Liability Company (LLC): Decisions are made by the owner or the board of members.
- Joint-stock company: Authority rests with the General Meeting of Shareholders (requires meeting minutes and a list of attending shareholders).
- Private enterprises: The business owner directly signs the relevant documents to carry out the business dissolution procedures.
Time and cost of completing the procedure
The cost and time involved in dissolution depend on the "cleanliness" of the company's tax records.
- Timeframe: In reality, it usually takes 3 to 6 months if the business has many tax-related issues that need to be explained during the dissolution process.
- Costs: Including government fees and consulting service fees. The MAN – Master Accountant Network recommends that businesses carefully review their books to minimize tax penalties incurred during this period by using these methods. tax settlement services professional.
Important note to avoid prolonging the dissolution process.
To ensure a smooth business closure process, managers need to pay special attention to the following:
- Closing the social insurance account: This is often a bottleneck if the business still owes insurance contributions or has not completed the procedures for returning insurance cards to employees during the business dissolution process.
- Asset and liability management: Debt payments must be made in order of priority (Salary -> Taxes -> Other debts).
- Record keeping: After completing the business dissolution procedures, accounting documents still need to be stored in accordance with the Accounting Law (usually for 10 years) to facilitate any potential audits.
If you require more in-depth support regarding legal and accounting matters during the process. business dissolution, For the most detailed guidance, please contact experienced consulting firms.
Frequently Asked Questions about Company Dissolution Procedures
Here are the answers to the 5 most common questions about business dissolution procedures:
Can a business that owes taxes be dissolved?
How long does the business dissolution process take?
Is it mandatory to publish a notice when dissolving a company?
What is the difference between business dissolution and business bankruptcy?
Is it possible to file for business dissolution online?
Conclusion regarding the business dissolution procedure.
The process of dissolving a business is a complex legal procedure, requiring absolute accuracy in tax records and asset liquidation commitments. Following the correct procedures not only helps business owners end their ventures smoothly but also eliminates long-term legal risks. Hopefully, this in-depth guidance from MAN – Master Accountant Network will be a useful reference for you in carrying out the steps to terminate your business operations in accordance with the law.
Contact information for MAN – Master Accountant Network
- Address: 19A, 43rd Street, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- Email: man@man.net.vn
Content production is overseen by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam auditors with over 30 years of experience in accounting, auditing, and financial consulting.