


Professional license: CPA Vietnam Auditors
Experience: Over 30 years of experience in Accounting, Auditing, and Financial Consulting.
The process of dissolving a business does not end when the business passes a resolution or decision to dissolve. The business must still liquidate assets, settle obligations in order of priority, handle tax obligations, terminate the operations of subsidiaries, and submit the dissolution registration documents. According to current regulations, Decree 296/2026/ND-CP Effective from July 23, 2026, and amends and supplements some provisions of Decree 168/2025/ND-CP on business registration.
Compiled and professionally reviewed: MAN – Master Accountant Network
Conditions for a business to be dissolved
Businesses can be dissolved in legally prescribed circumstances, but the dissolution process can only be completed when all debts and other financial obligations are fully settled and there is no ongoing dispute resolution process in court or arbitration. These conditions are stipulated in Article 207. Law on Enterprises No. 59/2020/QH14.
Cases of business dissolution
According to Article 207 of the Enterprise Law, an enterprise may be dissolved in the following main cases:
- The company's operating period, as stated in its Articles of Association, has expired without a decision to extend it.
- According to the resolution or decision of the competent authority corresponding to each type of business.
- The company no longer has the minimum number of members or shareholders required by law for a continuous period of 06 months without undergoing the procedure to change its business type.
- The business registration certificate is revoked, except where the Law on Tax Administration provides otherwise.
Conditions that must be met before dissolution
The core requirement is that the business must ensure that all debts and other financial obligations are paid off, and that it is not currently involved in any disputes in court or arbitration. Therefore, before starting the procedure, the business should simultaneously review its accounts payable, tax obligations, obligations to employees, remaining assets, and unfinished contracts.
The procedure for dissolving a business in a typical case.
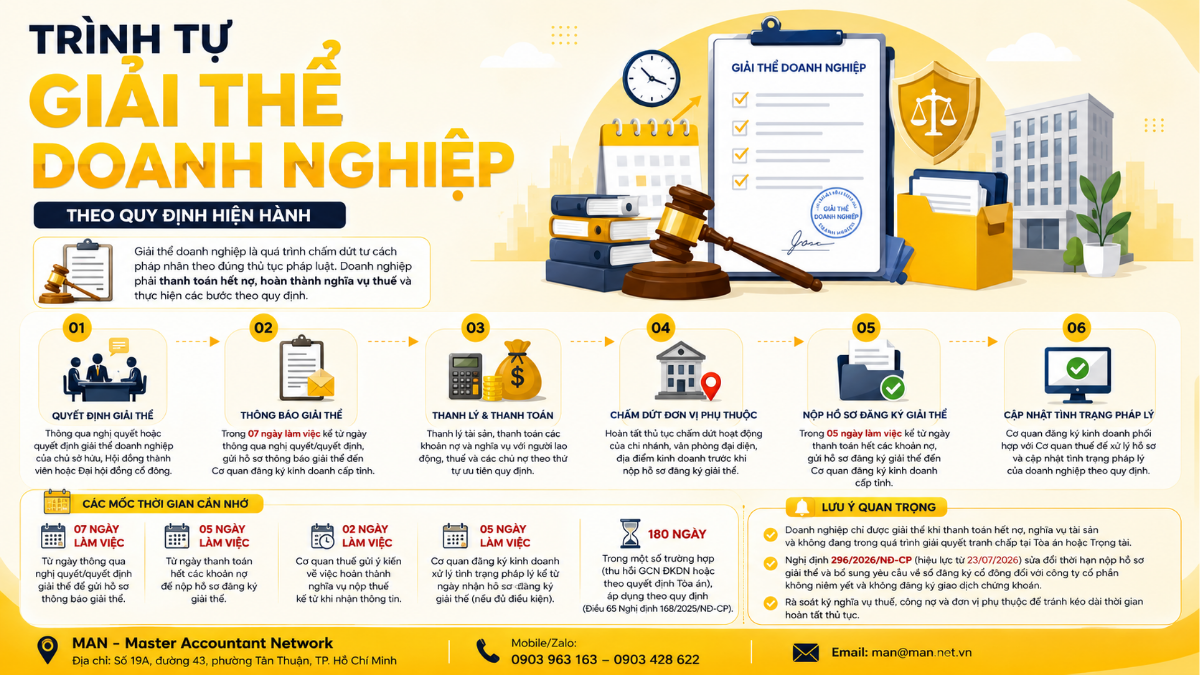
For dissolution cases under points a, b, and c of Clause 1, Article 207 of the Enterprise Law, the enterprise shall follow the following procedures: pass a resolution or decision on dissolution, send notices and documents within the specified timeframe, liquidate assets and settle debts, terminate the operations of subsidiary units, submit the dissolution registration dossier, and complete coordination with the Tax Authority. The basis for enterprise registration procedures is currently stipulated in... Decree 168/2025/ND-CP, as amended by Decree 296/2026/ND-CP.
Step 1: Pass a resolution or decision to dissolve the organization.
A resolution or decision on dissolution is the starting point of the process. It should include the name, registered office address, reason for dissolution, timeframe and procedures for contract liquidation, payment of debts, plan for handling obligations arising from employment contracts, and the signature of an authorized person according to the type of business.
Step 2: Submit the dissolution notification documents and publicly disclose the information.
Within 7 working days from the date of adoption of the resolution or decision on dissolution, the enterprise shall submit the required documents to the provincial business registration authority where its head office is located. This process is stipulated in Article 64 of Decree 168/2025/ND-CP.
Step 3: Liquidate assets and pay off debts.
Businesses proceed with asset liquidation and settlement of outstanding obligations. According to Article 208 of the Enterprise Law, debts are paid in order of priority, including those related to employees, tax debts, and other debts.
Step 4: Terminate the operations of branches, representative offices, and business locations.
Businesses with branches, representative offices, or business locations must address the operational status of these units during the dissolution process. This is an area that needs to be reviewed early to avoid a situation where the head office has completed all necessary steps but the dependent units still have outstanding obligations.
Step 5: Submit the business dissolution registration documents.
From July 23, 2026, businesses must submit dissolution registration documents within 5 working days from the date of full payment of all debts. This provision was amended in Clause 3, Article 64 of Decree 168/2025/ND-CP by Decree 296/2026/ND-CP.
Step 6: The business registration agency coordinates with the tax authority.
After receiving the dissolution registration application, the provincial business registration authority sends the information to the tax authority. According to the mechanism in Article 64 of Decree 168/2025/ND-CP, the tax authority sends its opinion on the fulfillment of tax obligations to the business registration authority to process the legal status of the enterprise according to the legally prescribed conditions.
Key milestones to remember: Businesses need to distinguish between the 7 working days from the date the resolution or decision to dissolve is passed and the 5 working days from the date all debts are paid in order to submit the dissolution registration application.
From an accounting perspective, businesses should reconcile accounting figures, liabilities, and tax obligations in parallel with the liquidation process. Further information on this topic can be found at [link/website]. tax accountant of NATO.
The procedure for dissolution when the business registration certificate is revoked or by court decision.
In cases where a business's business registration certificate is revoked or it is dissolved by a legally effective court decision, a separate mechanism is applied as stipulated in Article 65 of Decree 168/2025/ND-CP. The provincial business registration authority shall notify the status of the business undergoing dissolution procedures within the legally prescribed timeframe and conditions.
The business registration authority has announced that the company is undergoing dissolution procedures.
Within 3 working days from the date of the decision to revoke the business registration certificate or receiving the legally effective dissolution decision from the Court, the provincial business registration authority shall publish the decision, notify the status of the business undergoing dissolution procedures, and other related information in accordance with Article 65 of Decree 168/2025/ND-CP.
Pay off debts and file for dissolution registration.
After settling all debts, the enterprise submits the dissolution registration application in accordance with the procedures outlined in Article 65 of Decree 168/2025/ND-CP. The enterprise must still fulfill its financial obligations and obligations to employees as prescribed; this mechanism should not be interpreted as an exemption from obligations.
Handling cases where dissolution registration documents are not submitted.
Article 65 of Decree 168/2025/ND-CP stipulates the mechanism for handling the legal status after 180 days from the date the provincial business registration authority notifies the enterprise that it is undergoing dissolution procedures, provided that all legally required conditions are met. This deadline does not mean that the enterprise is exempt from tax obligations or debts.
Business dissolution documents
The dissolution registration dossier must reflect how the enterprise has disposed of its assets and obligations. According to Clause 1, Article 210 of the Enterprise Law, the dossier includes a Notice of Enterprise Dissolution, a Report on the Liquidation of Enterprise Assets, and a list of creditors along with the amount of debt paid, including tax debts and employee insurance contributions as prescribed.
Business dissolution registration documents
Essentially, businesses need to prepare the following sets of documents:
- Announcement regarding the dissolution of the business.
- Report on the liquidation of company assets.
- A list of creditors and the amounts paid, including tax debts and mandatory employee insurance contributions.
Additional documents for certain joint-stock companies
Decree 296/2026/ND-CP, effective from July 23, 2026, adds specific requirements for joint-stock companies that are not listed companies or companies registered for securities trading. Accordingly, the notice of dissolution in the business registration dossier must be accompanied by a copy of the shareholder register, as stipulated in the regulations.
Responsibility for the accuracy of records
Dissolution documents reflect the assets, liabilities, and obligations of a business at the time of cessation of operations. Therefore, those responsible must ensure the accuracy and truthfulness of the documents; accountants should reconcile accounting data, accounts payable, tax obligations, obligations to employees, and assets to be liquidated before finalizing the documents.
Key deadlines to remember when dissolving a business.
The following milestones help businesses distinguish when each term begins and who is responsible for its implementation. Not all milestones apply simultaneously to all dissolution cases.
| Timeline | From the time | The implementing entity or agency |
| 7 working days | Date the resolution or decision to dissolve was adopted | Businesses submit the required documents. |
| 05 working days | The date all debts are paid off. | The company submits the dissolution registration documents. |
| 2 working days | Date the Tax Authority receives the dissolution registration information | The tax authorities send their opinion on tax obligations. |
| 05 working days | Date the Provincial Business Registration Authority receives the dissolution registration application. | The business registration authority will process the legal status if all conditions are met. |
| 180 days | Date of notification that the business is undergoing dissolution procedures in cases falling under Article 65. | The business registration authority will process the application according to legal conditions. |
Specifically, the 5-day working-day deadline from the date of full payment of all debts needs to be compared with the regulations effective from July 23, 2026. Decree 296/2026/ND-CP.
Common mistakes businesses make when carrying out dissolution procedures.
Confusing the dissolution decision with the fact that the business has already been dissolved.
Passing a resolution or decision to dissolve is only the first step. The business still has to deal with assets, liabilities, tax obligations, subsidiaries, and dissolution registration documents before its legal status is updated as required by regulations.
Omitting branches, representative offices, and business locations.
Businesses with subsidiaries need to review each unit from the outset. Checking only the head office while neglecting branches, representative offices, or business locations can lead to unfinished tasks.
They haven't fulfilled their tax obligations but already want to complete the dissolution process.
Tax obligations are a crucial part of the dissolution process. Businesses should review their tax obligations alongside asset liquidation and debt settlement. For more in-depth review, consider MAN's tax settlement services.
Use the old procedure before July 23, 2026.
Decree 296/2026/ND-CP, issued and effective July 23, 2026, amends several provisions of Decree 168/2025/ND-CP. Businesses currently using internal forms or procedures established before this date should review them.
Confusion between ordinary dissolution and dissolution due to revocation of the business registration certificate.
The two cases have different handling mechanisms. Ordinary dissolution is carried out according to Articles 208 and 64; in cases where the business registration certificate is revoked or by court decision, it is handled according to Articles 209 and 65 of the respective documents.
If a business needs to review documents before proceeding, they can refer to the following: business dissolution services from MAN. If simultaneous processing of documentation and accounting/tax obligations is required, businesses can refer to additional information. comprehensive business dissolution services.
Conclude
The process of dissolving a business needs to be carried out in the correct order, rather than focusing solely on the final filing of documents. In a typical dissolution case, the business needs to pass a resolution or decision to dissolve, submit documents within the deadline, liquidate assets and settle obligations, terminate the operations of subsidiary units, then file the dissolution registration documents and complete the coordination process with the Tax Authority.
Two key deadlines to note are 7 working days from the date of adoption of the dissolution resolution or decision to submit the required documents, and 5 working days from the date of full payment of all debts to submit the dissolution registration dossier. Decree 296/2026/ND-CP is an important update for businesses implementing the procedure from July 23, 2026.
Frequently Asked Questions about the Business Dissolution Procedure
How long after paying off all debts do I have to file for dissolution?
Businesses must submit their dissolution registration documents within 05 working days from the date of full payment of all debts as stipulated by current regulations.
Does a business need to fulfill its tax obligations when it is dissolved?
Yes. The dissolution registration process involves coordination between the provincial business registration authority and the tax authority. Tax obligations must be settled according to regulations before the business's legal status is finalized.
Are regular dissolution and dissolution due to revocation of the business registration certificate the same thing?
They are not exactly the same. The two cases are governed by different procedures in the Enterprise Law and Decree 168/2025/ND-CP, therefore businesses need to identify the correct case before proceeding.
Legal basis
The key documents that need to be compared when carrying out the business dissolution procedure include:
- Law on Enterprises No. 59/2020/QH14 of the National Assembly.
- Decree 168/2025/ND-CP Government regulations on business registration.
- Decree 296/2026/ND-CP The Government amends and supplements several articles of Decree 168/2025/ND-CP.




