Professional license: CPA Vietnam Auditors
Experience: Over 30 years of experience in Accounting, Auditing, and Financial Consulting.
The Ministry of Finance has issued Decision 1933/QD-BTC dated July 20, 2026, on the announcement of administrative procedures that have been replaced or abolished in the field of tax management (termination of tax identification number upon dissolution). Accordingly, Section 8, Part II of the Appendix attached to the Decision specifies the procedure for terminating the validity of the tax identification number for each group of taxpayers. This is an important step in the process. business dissolution process, setting deadlines for filing documents along with mandatory tax obligations that must be fulfilled.
Procedure for terminating tax identification numbers according to Decision 1933/QD-BTC
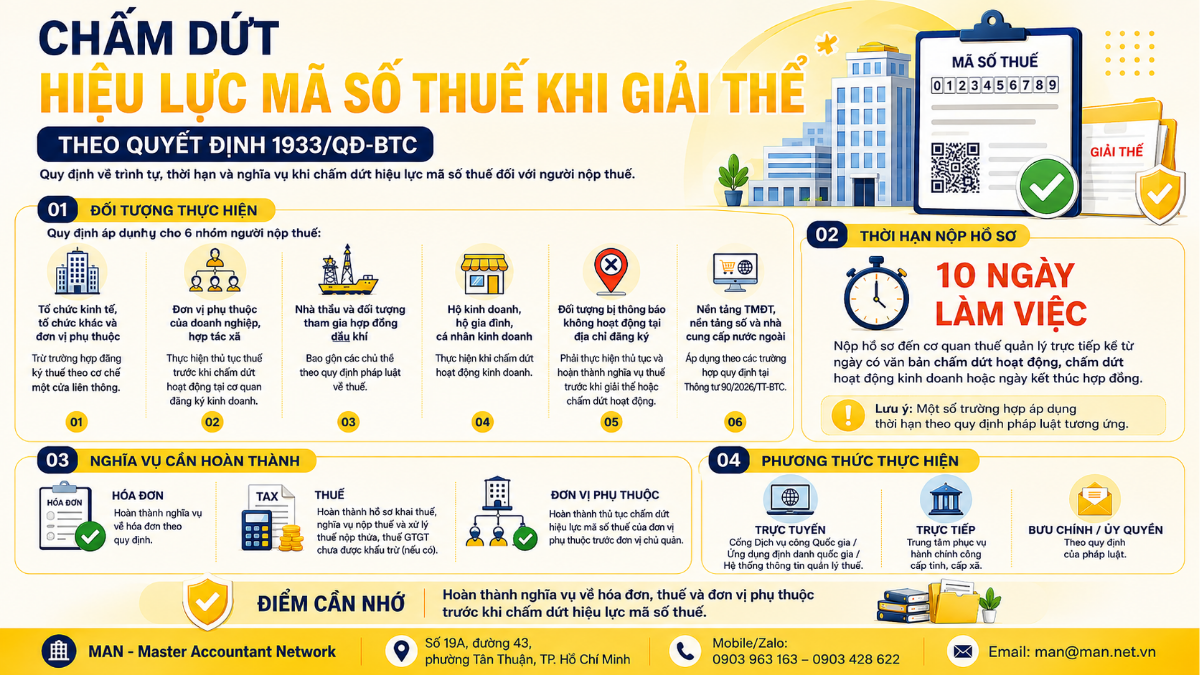
The Ministry of Finance issued Decision 1933/QD-BTC dated July 20, 2026, announcing the replacement of administrative procedures in the field of tax management. In Section 8, Part II of the Appendix attached to Decision 1933/QD-BTC, the procedure for terminating tax identification numbers is specifically categorized for six groups of taxpayers.
The procedure for each group of taxpayers is as follows:
- Economic organizations, other organizations and dependent units (except for tax registration through the integrated one-stop mechanism via the business registration agency)Submit the application for termination of the tax identification number to the directly managing tax authority within 10 working days from the date of the document terminating the operation, business activity, or contract termination.
- Subsidiary units of enterprises, subsidiary units of cooperativesBefore submitting the application: Terminate the operations of branches and representative offices. at the business registration office above National portal for business registration, The entity must submit the application to the directly managing tax authority to carry out the procedures and fulfill its tax obligations within the deadlines stipulated in the 2020 Enterprise Law, the 2023 Cooperative Law, and relevant laws. If these laws do not specify a deadline, the application must be submitted within 10 working days from the date of the decision or notification regarding the termination of operations of the branch, representative office, business household, or the decision to revoke the business registration certificate.
- Foreign contractors, foreign subcontractors, operators, joint ventures, organizations assigned by the Vietnamese Government to receive Vietnam's share of oil and gas fields in overlapping areas, contractors, investors participating in oil and gas contracts, and the parent company – Vietnam National Energy Corporation representing the host country – receive the share of profits from oil and gas contracts.Submit the application for termination of the tax identification number to the directly managing tax authority within 10 working days from the date of contract termination or from the date of transfer of all participating rights in the oil and gas contract.
- Household businesses, family businesses, and individuals engaged in production and business activities.Submit the application to the directly managing tax authority within 10 working days from the date of business cessation. In the case of electronic tax registration, taxpayers access the National Public Service Portal, the National Identification Application, or the Tax Management Information System to create the application and electronically verify the individual taxpayer or their legal representative (including biometric information as prescribed for electronic identification and verification and the tax authority's roadmap).
- Businesses, cooperatives, partnerships, and subsidiary units that have been notified by the tax authorities as not operating at their registered address.Before submitting the dissolution application for a business or cooperative (including voluntary and compulsory dissolution) or termination of operations to the business registration authority, taxpayers must go to the directly managing tax authority to submit the application, carry out tax procedures, and fulfill tax obligations as prescribed.
- Owners of e-commerce platforms, digital platforms subject to withholding and payment on behalf of others, and foreign suppliers.This applies to the entities specified in points g and h, Clause 2, Article 13 of Circular 90/2026/TT-BTC. The owner of a digital platform, when it no longer has the function of online ordering and payment, or a foreign supplier when it ceases business operations in Vietnam, must submit a dossier to terminate the validity of their tax identification number within 10 working days from the date of the document terminating the operation, business activities, or contract.
Deadline for submitting documents to terminate tax identification number.
According to point h, clause 1, Article 6 of Decree 252/2026/ND-CP, taxpayers must submit the application for termination of their tax identification number to the directly managing tax authority within 10 working days from the date of the written notice of cessation of operations, cessation of business activities, or contract termination. For specific cases, the deadline for implementation will be applied according to the corresponding provisions of specialized laws.
Procedure for terminating a tax identification number.
Taxpayers can terminate their tax identification number through the following application submission methods:
- OnlineSubmit via National Public Service Portal, National Identification Application or Tax Management Information System. The application of electronic transactions complies with the roadmap of the tax authority as stipulated in Clause 2, Article 36 of Circular 90/2026/TT-BTC.
- DirectSubmit at the provincial or commune-level public administrative service center.
- Postal or authorizedPayment can be made through public postal services, by hiring services from businesses or individuals, or through authorization as prescribed by law.
Tax obligations must be fulfilled before the tax identification number expires.
According to Article 14 of Circular 90/2026/TT-BTC, effective from July 1, 2026, taxpayers must fulfill their obligations as prescribed before their tax identification number expires.
Specific obligations include:
- Fulfill all invoicing obligations as required by law.
- Complete the obligations of filing tax returns, paying taxes, and handling any overpaid taxes and uncredited value-added tax (if any) as stipulated in point d.1, clause 1, Article 7 of Decree 252/2026/ND-CP.
- In cases where the parent company has subsidiary units, all subsidiary units must complete the procedure for terminating their tax identification numbers before terminating the parent company's tax identification number.
Recommendations for compliance from MAN – Master Accountant Network
Based on the regulations in Decision 1933/QD-BTC, Decree 252/2026/ND-CP, and Circular 90/2026/TT-BTC, the professional team at MAN – Master Accountant Network provides operational guidelines for businesses when applying these regulations. business dissolution services or perform the procedure yourself:
- For cases where a notification is received indicating inactivity at the registered address.Taxpayers in this group must work with the directly managing tax authority, complete tax procedures, and fulfill their tax obligations before submitting dissolution or cessation of operations documents to the business registration authority.
- Order of execution between the managing unit and the subordinate unitThe managing entity must complete the procedures for terminating the tax identification numbers of all dependent units before terminating the tax identification number of the managing entity itself, as stipulated in Article 14 of Circular 90/2026/TT-BTC.
- Perform electronic authentication.For cases where electronic tax registration applications are submitted and fall under the applicable regulations, taxpayers must perform electronic authentication in accordance with the identification procedures and timelines set by the tax authorities.
- Determine the starting point for calculating the 10-working-day milestone.For cases where the 10-working-day timeframe applies, the period is calculated from the date of the written termination of operations, cessation of business activities, or the contract termination date as stipulated accordingly.
Conclude
Decision 1933/QD-BTC announces the administrative procedure for terminating the validity of tax identification numbers, which has been replaced, along with the detailed regulations in Decree 252/2026/ND-CP and Circular 90/2026/TT-BTC, clearly stipulating the order, time limit, and method of implementation for each group of taxpayers.
To ensure a smooth dissolution process, businesses should proactively review their invoicing obligations, tax returns, and any outstanding or overpaid taxes before drafting the termination document. They can also consult with relevant authorities for further information. tax consulting services Professionalism aims to ensure legal compliance.
Data source: Decision 1933/QD-BTC, Decree 252/2026/ND-CP, Circular 90/2026/TT-BTC (See also) Law Library)