


The process of dissolving a company with the tax authorities is one of the most complex and crucial steps in the entire business closure process. In fact, it is an important part of the overall procedure. business dissolution procedures As stipulated by current law, fulfilling financial obligations and terminating tax identification numbers often takes longer than processing at the business registration agency. Many business owners face difficulties due to a lack of understanding of the settlement process, leading to delays of months and even administrative penalties for late filing. Understanding the following procedures will help managers be more proactive in handling their applications.
What are the procedures for dissolving a company with the tax authorities?
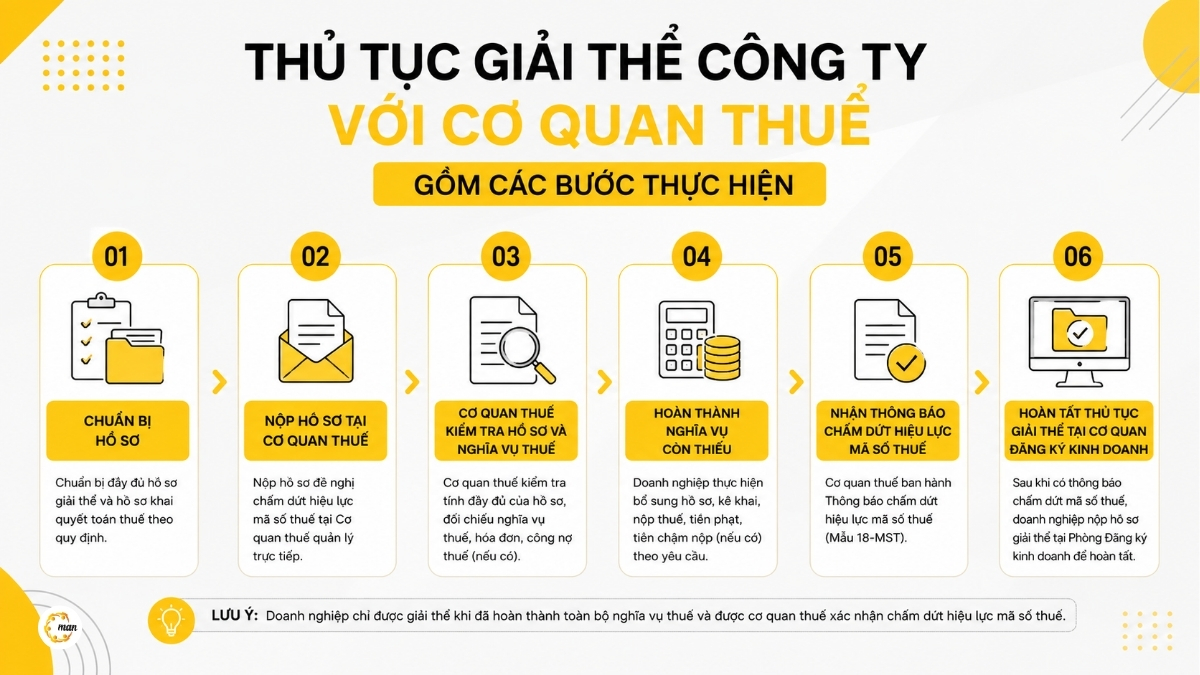
Process summary: The procedure for dissolving a company with the tax authorities is essentially a process of tax settlement and termination of the tax identification number. Businesses need to fulfill all tax declaration, tax payment, and invoice cancellation obligations before the tax authorities issue the Notice of Termination of Tax Identification Number (Form No. 18-MST).
The role of tax procedures in the business dissolution process.
In the process of terminating the existence of a legal entity, the company dissolution procedure at the tax authority plays a crucial role. According to the provisions of the Enterprise Law No. 59/2020/QH14, enterprises can only complete the registration procedures after the dissolution process is complete. business dissolution at the Business Registration Office under the Department of Planning and Investment after fulfilling all tax obligations.
To help business managers better understand business dissolution process In addition to clearly distinguishing the roles and responsibilities of each state management agency throughout this process, the following comparison table summarizes the fundamental differences:
| Comparison criteria | Tax authority (Tax Department or Tax Office) | Business Registration Office (Department of Planning and Investment) |
|---|---|---|
| Main task | Conduct tax compliance checks, recover outstanding debts, and terminate the validity of the business's tax identification number. | Revoke the business registration certificate and remove the business name from the national business register. |
| Procedure | Submit tax settlement documents, reconcile tax liabilities, and process invoice cancellations. | File the formal dissolution documents after the tax identification number has expired. |
| Output | Notification of Termination of Tax Identification Number (Form No. 18-MST) | Decision to dissolve and notification that the business has ceased operations. |
This clear distinction shows that procedures at the tax authority are always a mandatory condition before a business can officially have its name removed from the National Business Registration Portal.
When does a business need to terminate its tax identification number?
The specific timeframe for businesses to terminate their tax identification number is stipulated in Law No. 38/2019/QH14 on Tax Administration and Circular No. 105/2020/TT-BTC. Immediately after receiving a dissolution decision from the company owner, the Board of Members, or the General Meeting of Shareholders, the business must submit the application. Terminate the tax identification number. Report to the tax authority directly responsible for management within 10 working days from the date of issuance of the dissolution decision.
Delays in implementation not only prolong the dissolution process but also increase the risk of incurring late payment penalties and administrative fines for failing to submit periodic tax returns on the eTax electronic tax system within the legally mandated deadline.
Documents required for company dissolution procedures with the tax authorities.
To proceed with the next steps of the procedure, it is necessary to prepare a set of business dissolution documents Submitting accurate information to the tax authorities is absolutely essential for every business.
List of required documents
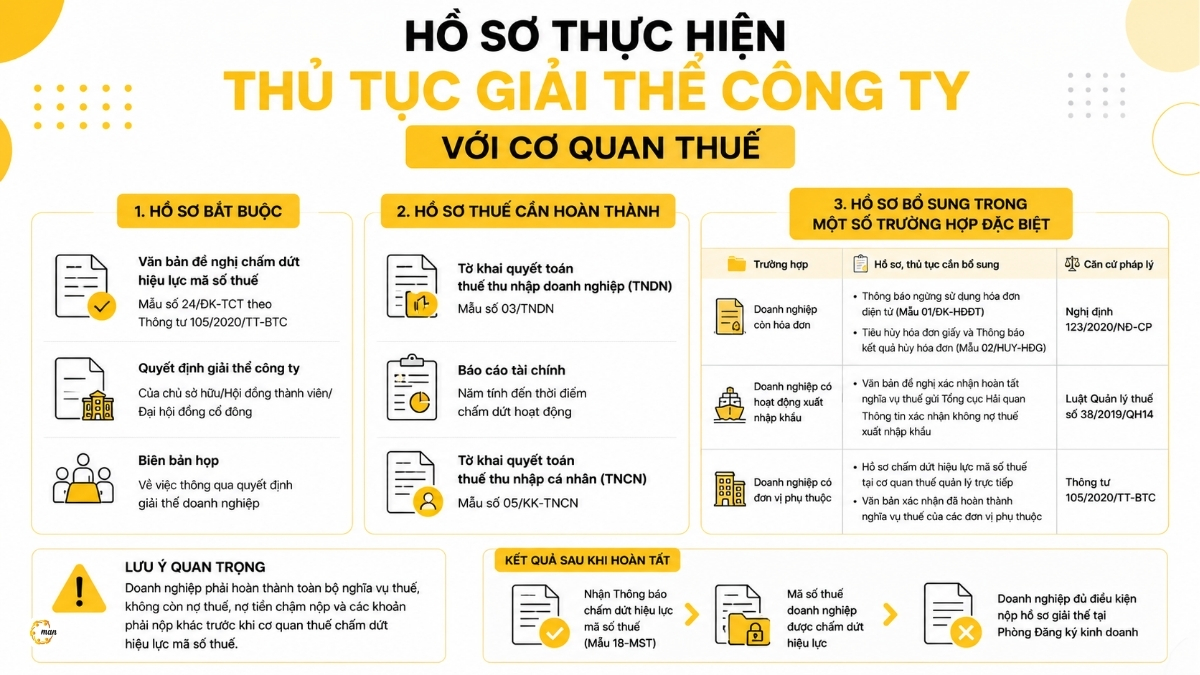
For the tax authorities to accept the request to terminate the tax identification number, businesses need to prepare a complete set of documents as guided by Circular 105/2020/TT-BTC. The fundamental legal documents that must be included in this set of documents are:
- The request for termination of the tax identification number follows Form No. 24/ĐK-TCT issued with Circular 105/2020/TT-BTC.
- The dissolution decision of the owner for a single-member limited liability company, or of the Board of Members for a limited liability company with two or more members (applicable when carrying out the procedure). Dissolution of a limited liability company), or of the General Meeting of Shareholders for joint-stock companies (applicable when carrying out the procedure) Dissolution of a joint-stock company).
- A copy of the minutes of the meeting of the Board of Members or the General Meeting of Shareholders regarding the approval of the decision to dissolve the business.
These are the core legal documents proving the legitimacy of the request to terminate the tax identification number and begin the formal tax settlement process.
Tax returns must be completed before submission.
In addition to the administrative documents mentioned above, businesses must proactively complete tax declaration documents up to the time of the dissolution decision. The tax finalization declaration dossier includes the following basic components:
- Corporate income tax return form No. 03/TNDN.
- Financial statements for the year up to the point of business cessation.
- Personal Income Tax (PIT) Final Settlement Declaration Form No. 05/KK-TNCN.
Businesses should note that any tax periods that have not been declared or paid must be fully supplemented before proceeding to the next steps.
Documents in certain special cases
Depending on their specific operational characteristics prior to dissolution, some businesses may need to prepare additional specific documents to complete tax procedures. The table below details the required supplementary documents for each specific group:
| Applicable subjects | Additional documents and records are required. | Relevant legal basis |
|---|---|---|
| The business still has invoices. | – Report on the use of invoices (Form BC26/AC)
– Notification of invoice cancellation results (Form TB03/AC) |
Decree 123/2020/ND-CP |
| Businesses engaged in import and export activities. | – A written request for confirmation of fulfillment of import and export tax payment obligations submitted to the General Department of Customs. | Law on Tax Administration No. 38/2019/QH14 |
| Businesses with subsidiaries | – Notification of termination of tax identification numbers for all branches, representative offices, and business locations under its jurisdiction. | Circular 105/2020/TT-BTC |
These specific documents need to be processed completely before the business can proceed with submitting the application to terminate the parent company's tax identification number.
Document checklist before submission
To minimize errors that could lead to rejected documents or requests for additional corrections, businesses should self-assess the documentation items according to the list below:
- The information on the application form for termination of tax identification number (Form No. 24/ĐK-TCT) has been filled out completely and accurately.
- The decision to dissolve the business must be signed by the legal representative and all contributing members or founding shareholders.
- Minutes of the Board of Members or General Meeting of Shareholders must be fully and clearly signed and stamped with a seal if there are multiple pages.
- I have completed the submission of value-added tax (VAT), personal income tax (PIT), and corporate income tax (CIT) returns for all outstanding tax periods.
- The corporate income tax and personal income tax returns have been filed up to the time of dissolution.
- I have completed the procedure to cancel unused electronic invoices on the system and received confirmation from the tax authorities.
- All outstanding taxes and any applicable penalties, including any late payment interest, have been paid in full.
- We have received a confirmation letter from the General Department of Customs stating that the business, which is registered for import and export activities, has no outstanding tax debts.
- The procedure for terminating the tax identification numbers of all affiliated subsidiaries has been completed.
- Once all the checkboxes are checked and confirmed, the business can confidently submit the application to the tax authority's online system to begin the assessment process.
Procedures for dissolving a company with the tax authorities.
Step 1. Prepare the documents.
The business owner and accounting department collect all invoices, accounting records, and tax payment documents from the company's inception or from the most recent tax settlement period. The completeness of this documentation directly impacts the processing speed in subsequent steps.
Step 2. Submit the application to the tax authority.
Businesses can submit their applications online through the General Department of Taxation's electronic portal or submit paper applications directly at the one-stop service counter of the Tax Sub-department or the Tax Department directly managing the business.
Step 3. The tax authority checks the records and tax obligations.
After receiving the application, the tax authority will assign a specialized officer to review the company's data on the centralized tax management system.
Check the completeness of the file.
Tax officials will compare the documents in the submitted file with legal regulations. If the file is incomplete or does not conform to the prescribed form, the tax authority will issue a notice requesting additional information as soon as possible.
Check the status of tax declarations and payments.
The management staff conducts a thorough review of the entire system to check whether the business has submitted all VAT, corporate income tax, personal income tax returns, and financial reports over the years, and also compares the amount of tax paid with the amount of tax due as stated in the returns.
Check the invoice and related obligations.
The system will scan the business's electronic invoice usage status. The tax authority will check whether the business has reported the cancellation of all unused invoices and compare the revenue on the electronic invoices with the revenue declared on the VAT tax returns.
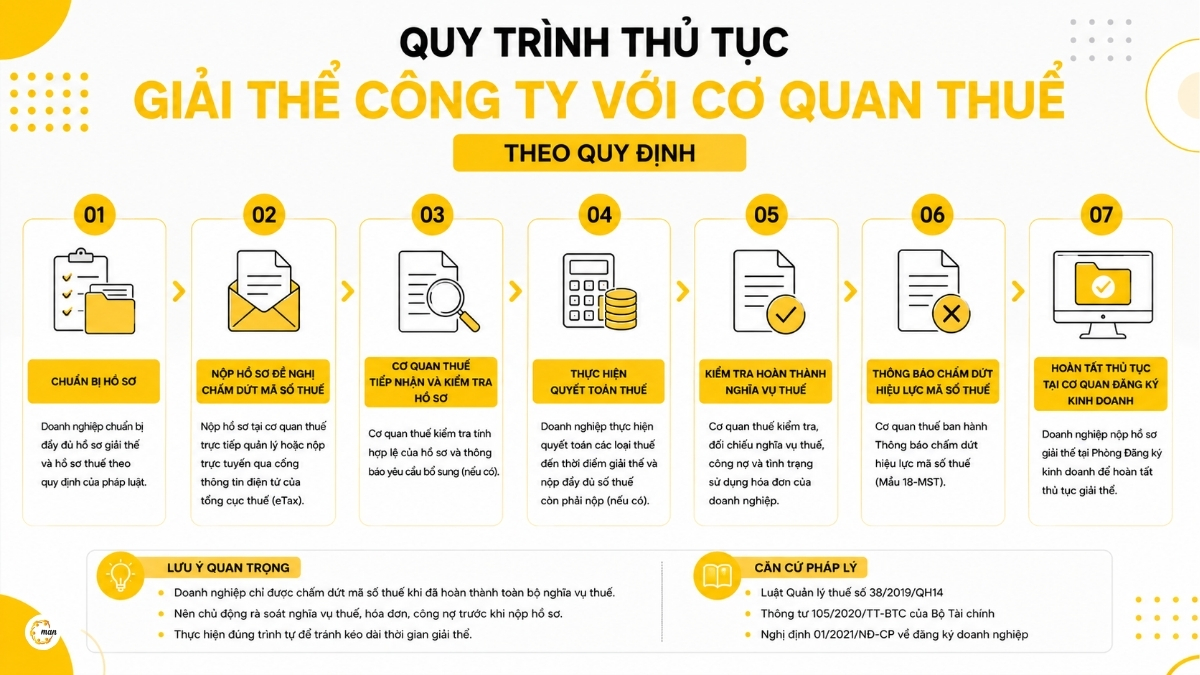
Step 4. Complete any remaining obligations.
If the tax authorities discover that a business has outstanding tax debts, has not submitted tax returns, or has discrepancies in accounting data, the business must immediately file supplementary tax returns and pay the additional tax and late payment penalties to the State Treasury.
Step 5. Receive notification of tax code termination.
Once the business has fulfilled all financial obligations and its documentation has been approved, the tax authority will issue a Notice of Termination of Tax Identification Number (Form No. 18-MST). This is the highest legal document confirming that the business has completed the tax procedures and can proceed to the next step at the Department of Planning and Investment.
Each step in the process of terminating a tax identification number requires precise timing and sequence, as shown in the timeline below:
| Step | Job details | Implementing agency | Output |
|---|---|---|---|
| Step 1 | Through the decision to dissolve and prepare the relevant documents. | Internal business operations | Decision and minutes of the dissolution meeting |
| Step 2 | Submit an application to terminate the tax identification number. | The Tax Sub-department or the Tax Department directly manages the area. | Appointment slip or notification of application acceptance |
| Step 3 | Inspection and verification of tax obligations and settlement. | The tax authorities cooperate with businesses. | Tax audit report |
| Step 4 | Correct any errors, pay taxes and penalties incurred. | Businesses make payments to the Treasury. | Receipt for payment into the state budget |
| Step 5 | Issue a document confirming the closure of the tax identification number. | competent tax authority | Notification Form No. 18-MST |
Based on the roadmap above, businesses can proactively arrange personnel and prepare the corresponding finances for each stage of working with the tax authorities.
Corporate tax obligations must be fulfilled before dissolution.
Complete any missing tax returns and reports.
Before closing their tax identification number, businesses are obligated to submit all outstanding tax returns from previous tax periods. Any omissions in submitting monthly or quarterly returns must be fully completed.
Settlement of various taxes
Implementation tax settlement upon dissolution Corporate income tax and personal income tax settlement are mandatory obligations for all businesses operating normally before ceasing operations. Businesses need to clearly determine the amount of tax payable for the last tax period up to the date of the dissolution decision to serve as the basis for accurate settlement within the deadlines stipulated by current tax laws.
Report on invoice usage
Businesses that use invoices must submit a report on invoice usage for the final tax period. A complete report helps tax authorities monitor the number of invoices issued and used by the business.
Processing outstanding invoices
All unused electronic invoices must be canceled through the system. Businesses are strictly prohibited from issuing new invoices from the date the dissolution decision takes effect, except with the written consent of the tax authorities to handle inventory and liquidated assets.
Pay taxes, late payment penalties, and fines (if any).
All tax debts arising within the tax authority's management system, including late payment penalties and administrative fines for tax violations, must be fully settled into the state budget.
Fulfill any obligations to the Customs authorities (if applicable).
For businesses operating in the import and export sector, fulfilling tax obligations with the Customs authorities is a necessary condition for the tax authorities to proceed with the next steps of closing the tax identification number.
Before the tax authorities approve the deactivation of the tax identification number, businesses are required to fulfill their financial obligations and submit tax reports according to the detailed list below:
| Tax obligations | Detailed job description | Mandatory implementation time |
|---|---|---|
| Submit tax return | Complete all missing periodic tax returns (monthly, quarterly). | Before submitting the application to close the tax identification number. |
| Tax settlement | Prepare the final corporate income tax and personal income tax returns for the period. | According to the deadlines stipulated by current tax laws. |
| Cancel invoice | Cancel unused invoices on the electronic invoicing system. | Before submitting the application to terminate the tax identification number. |
| Paying off tax debts | Pay all outstanding taxes, late payment penalties, and fines. | Before receiving notification form 18-MST |
| Customs obligations | Please confirm that you have no outstanding import/export tax debts. | Before filing a tax return at the tax office. |
Reviewing and fulfilling these obligations on time is a prerequisite for preventing delays in processing applications at the relevant agency.
Timeframe for processing company dissolution procedures with the tax authorities.
Processing time as per regulations
According to the Law on Tax Administration, within 5 working days from the date of receiving a valid application for termination of the tax identification number, the tax authority must notify the national information system that the tax identification number has changed to the status of "inactive but has not completed tax registration procedures".
Total time of company dissolution In general, and the time it takes to fulfill tax obligations in particular, depends heavily on the size, accounting records, and actual figures of the business, and in practice, it often takes from a few weeks to a few months.
Cases that cause delays in processing applications.
The tax dissolution process is often delayed due to various subjective and objective reasons:
- The company's accounting records have been lost, and the data declared over the years contains significant discrepancies that require time for verification and explanation.
- The company has not completed the process of terminating the tax identification numbers for its branches or representative offices in other localities, resulting in the system being unable to approve the deactivation of the parent company's tax identification number.
- The process of waiting for confirmation from the Customs authorities that there are no outstanding tax debts has been prolonged due to difficulties in cross-referencing import and export data.
- Businesses that still owe taxes or late payment penalties but have not fully paid them into the state budget, including small amounts arising from minor discrepancies in the calculation of late payment penalties in the system.
To minimize this risk, a thorough review of accounting data before filing is essential for every business.
Important notes when carrying out company dissolution procedures with the tax authorities.
Common errors that lead to requests for additional information in applications.
During the process, businesses often encounter several common errors that lead to their applications being rejected or requiring further clarification:
- Misusing the form for requesting the termination of a tax identification number or failing to fill in the legal representative's information.
- The dissolution decision incorrectly states the effective date or contains inconsistent information between the decision and the minutes of the Board of Members' meeting.
- Failure to properly cancel unused electronic invoices or submit the final invoice usage report.
These elementary mistakes are entirely preventable if businesses carefully check their documents before submitting them.
Reasons why the tax authorities have not yet approved the termination of the tax identification number.
The tax authorities will refuse to issue Form 18-MST Notice if the business falls under any of the following cases:
- The company has not yet fulfilled its financial obligations: This is not permitted by law. Dissolve businesses that owe taxes., Therefore, all outstanding tax debts, late payment penalties, and fines must be paid in full.
- Currently undergoing a tax audit or inspection, or with outstanding tax-related complaints or disputes.
- The tax obligations of subsidiary units such as branches and representative offices have not yet been fulfilled.
Therefore, businesses need to coordinate closely with the tax authorities to thoroughly resolve these issues before proceeding to the final step.
Ways to shorten document processing time
Based on the experience of MAN's team of experts in handling dissolution cases, the time required for tax settlement largely depends on the completeness of the company's accounting system. To expedite the processing of dissolution applications and optimize efficiency, we offer solutions to help speed up the dissolution process. business dissolution costs Overall, businesses can implement the following solutions:
- Proactively review and clean up your accounting records, invoices, and supporting documents before submitting official documents to the tax authorities.
- Maintain regular contact and seamless communication with your direct tax officer to stay updated on progress and provide explanations of data as soon as required.
- In cases where businesses encounter difficulties with documentation or lack a dedicated department for data review, seeking assistance from a professional is a viable option. MAN business dissolution services Professionalism will help businesses overcome difficulties quickly, ensuring accuracy and compliance with legal regulations.
Thorough preparation of accounting data will help businesses navigate the tax settlement process as smoothly as possible.
What should I do after receiving notification that my tax identification number has expired?
After receiving the Notice of Termination of Tax Identification Number (Form No. 18-MST) from the tax authority, the enterprise must submit the official dissolution application to the Business Registration Department under the Department of Planning and Investment within the prescribed time limit to complete the removal of the enterprise's name from the National Business Registration Book.
A factual note: During the process of assisting numerous businesses with dissolution, legal experts have compiled the following important practical tips to help business owners avoid legal pitfalls and save time:
- Maintain consistent communication with your direct tax officer: Each business has a tax officer directly managing its records. Maintain regular contact to promptly update any requests for amendments to tax settlement figures.
- Pay off all outstanding penalties, even if it's just a single dollar: The General Department of Taxation's system will not automatically approve the closure of a tax identification number if the electronic tax account still records any outstanding debts, including amounts arising from exchange rate differences or late payments of a few hundred dong.
- Accounting records must be retained for a minimum of 10 years. Even after successful dissolution, the original documents should still be carefully stored in case they are inspected by competent authorities later.
These practical insights will help businesses proactively control the tax code closure process safely and cost-effectively.
Conclude
The process of dissolving a company with the tax authorities requires a high degree of accuracy and transparency in preparing documents and processing accounting data. To avoid unnecessary legal risks and shorten the completion time, businesses need to proactively review their documentation system, fulfill all tax obligations, and closely monitor the processing progress. Thorough preparation at the tax authority stage is key to a smooth business dissolution process. If businesses encounter difficulties or require in-depth support during the process, the team of experts at MAN – Master Accountant Network is always ready to assist in resolving legal and financial procedures most effectively.
Contact MAN – Master Accountant Network for consultation.
If your business needs advice on accounting, auditing, taxation, investment capital settlement, or other corporate financial services, our team of experts is here to help. MAN – Master Accountant Network Always ready to assist.
Contact information
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Content specialist
The content has been compiled, reviewed, and professionally vetted by Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam auditor with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
MAN – Master Accountant Network is committed to providing accurate, objective, and up-to-date information in accordance with current legal regulations. All professional content is built on practical experience, adheres to professional standards, and aims to provide reliable reference value for businesses, organizations, and individuals.




