


The timeframe for dissolving a business is determined on a case-by-case basis, not a fixed period from the moment the business makes the decision until its status is updated to "dissolved". For businesses that proactively dissolve, notable milestones include 7 working days to submit the dissolution resolution or decision; 10 working days in some cases of tax code termination; 45 days to submit tax return documents; and 5 and 2 working days during the dissolution registration phase.
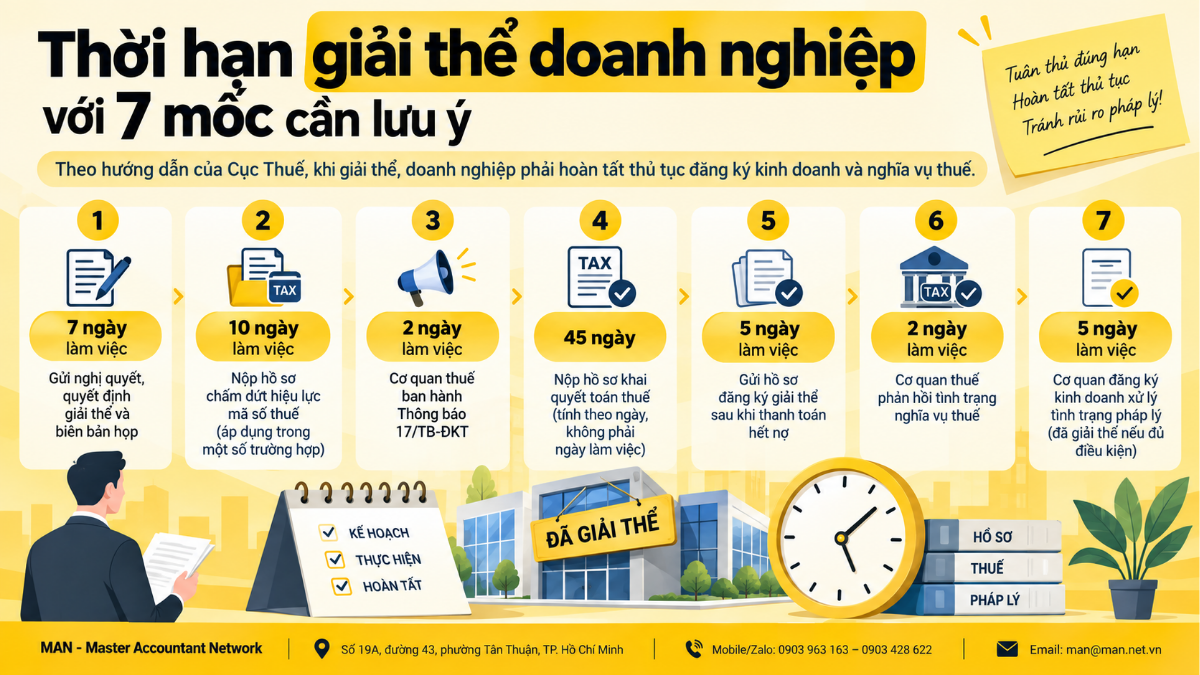
7 key deadlines to watch when dissolving a business.
The seven milestones below help businesses, owners, directors, and accounting departments determine the right time to fulfill obligations or wait for government agencies to process documents.
| Mold | Duration | Main content |
| 1 | 7 working days | Send the resolution, dissolution decision, and meeting minutes. |
| 2 | 10 working days | Submit the application to terminate the tax identification number if it must be done in person. |
| 3 | 2 working days | The tax authority issued Notice 17/TB-ĐKT |
| 4 | 45 days | Submit tax return documents. |
| 5 | 05 working days | Submit the dissolution registration documents after all debts have been paid. |
| 6 | 2 working days | The tax authority responds regarding the tax liability status. |
| 7 | 05 working days | The business registration authority will process the legal status if all conditions are met. |
Send the resolution or decision on dissolution within 7 working days.
The first milestone in the business dissolution process is 7 working days from the date of adoption of the resolution or decision to dissolve. (According to Clause 3, Article 208) Enterprise Law 2020, Resolutions, dissolution decisions, and meeting minutes must be sent to the business registration authority, the tax authority, and the employees of the enterprise.
Resolutions and decisions on dissolution must also be published on the National Business Registration Portal and publicly displayed at the head office, branches, and representative offices. If the enterprise still has outstanding financial obligations, the resolution, decision on dissolution, and debt settlement plan must be sent to creditors and other parties with related rights and obligations.
Submit the application to terminate the tax identification number within 10 working days.
The 10-working-day deadline for business dissolution does not apply to all cases. This deadline applies to taxpayers who must carry out procedures directly with the tax authorities, including certain cases where branches or representative offices cease operations and where business law or related laws do not specify a deadline.
According to Clause 5, Article 13 Circular 90/2026/TT-BTC, The application must be submitted to the directly managing tax authority within 10 working days from the date of the decision or notice of termination of operations, or from the date of the decision to revoke the business registration certificate. The application includes a written request to terminate the tax identification number (form 24/ĐKT) and supporting documents proving the termination of operations.
For businesses dissolving through the integrated process, it's necessary to distinguish between procedures at the business registration agency and tax registration procedures. Businesses are not automatically required to submit Form 24/ĐKT to initiate procedures at the tax agency if their application is processed through the integrated system, unless required by tax law or a notification from the tax agency. Further verification is possible. Instructions on terminating the tax identification number upon dissolution of MAN..
The tax authority issued Notice 17/TB-ĐKT within 2 working days.
The notification indicates whether the file is subject to an on-site inspection by the taxpayer. If it is subject to inspection, the tax authority specifies the expected time for the inspection. After the notification is issued, the tax identification number is changed to status 03, meaning it is inactive but the procedure for terminating its validity has not yet been completed.
During the business dissolution period, the tax authority specifies a 2-working-day processing timeframe after receiving all necessary documents for terminating the tax identification number. According to point a.1, clause 1, Article 15 of Circular 90/2026/TT-BTC, the tax authority issues Notice Form 17/TB-ĐKT regarding the taxpayer's cessation of operations and ongoing procedures for terminating their tax identification number.
Submit your tax return no later than the 45th day.
A key milestone in the business dissolution process is the 45th day for filing tax returns. This is in accordance with point b, clause 5, Article 10. Decree 252/2026/ND-CP, Tax return documents must be submitted no later than 45 days from the date the taxpayer receives a decision on cessation of operations, dissolution, bankruptcy, or a corresponding case as prescribed.
Businesses need to review their corporate income tax settlement records up to the time of cessation of operations, including the tax return, financial statements, and related appendices based on actual transactions. If there were income payments from salaries and wages, personal income tax settlement must be carried out according to regulations; if no income payments were made, no personal income tax settlement records need to be submitted.
The 45-day period is calculated in days, not working days. When planning the dissolution of a business, accountants should clearly state the start date and the end date. If a review of records and tax obligations up to the time of cessation of operations is needed, the business can refer to relevant resources. MAN's corporate tax settlement services.
Submit the dissolution registration documents within 5 working days after all debts have been settled.
After all debts have been settled, the next deadline in the business dissolution process is 5 working days to submit the dissolution registration documents. (According to Clause 3, Article 64) Decree 168/2025/ND-CP, The application is submitted to the provincial business registration authority where the enterprise has its head office.
This regulation should be read along with Decree 296/2026/ND-CP, This regulation, effective from July 23, 2026, amends and supplements Decree 168/2025/ND-CP. The 5-day working period remains unchanged. Furthermore, the dissolution registration dossier must comply with Clause 1, Article 210 of the Enterprise Law; for joint-stock companies that are not listed companies and not registered for securities trading, the dissolution notice must also include a copy of the shareholder register.
Before submitting the application, businesses need to review the termination of operations of branches, representative offices, and business locations, if any. Further verification may be necessary. Instructions for registering the dissolution and the procedures to follow for MAN..
The tax authority will respond regarding the status of your tax obligations within 2 business days.
The next two working days within the business dissolution period belong to the tax authority. After receiving the dissolution registration dossier, the provincial business registration agency sends information about the business's dissolution registration to the tax authority. According to Clause 5, Article 64 of Decree 168/2025/ND-CP, within two working days from the date of receiving the information, the tax authority sends its opinion on the fulfillment of tax obligations to the business registration agency.
This is the tax authority's processing deadline, not the deadline for the business to submit a separate set of documents. Businesses should monitor the processing status and proactively review their tax obligations, invoices, and tax liabilities throughout the dissolution process.
Businesses can conduct further verification. Company dissolution procedures with the tax authorities and required documents. of NATO.
The business registration authority processes legal matters within 5 working days.
The deadline for dissolving a business is 5 working days from the date of receiving the dissolution registration application. According to Clause 5, Article 64 of Decree 168/2025/ND-CP, the provincial business registration authority changes the legal status of the business to "dissolved" if it does not receive an opinion from the tax authority or receives confirmation that the business has fulfilled its tax obligations.
The business registration authority simultaneously publishes the notice of business dissolution on the National Business Registration Portal. If the tax authority rejects the dissolution due to the business's failure to fulfill its tax obligations, the provincial business registration authority will notify the business. Therefore, the expiration of 5 working days does not automatically mean that all cases will be declared "dissolved".
To compare the entire sequence and processing steps, businesses can view them. Procedures for dissolving a business according to current regulations. of NATO.
How to control the deadline for business dissolution
The milestones in the business dissolution process arise from different events and therefore cannot be mechanically added together to form a single total number of days. Businesses should create separate tracking tables for each deadline, distinguishing between deadlines under their responsibility and those handled by government agencies.
When monitoring the deadline for business dissolution, the accounting department and the person in charge of the paperwork should focus on the following points:
- Record the exact date the resolution or decision to dissolve was adopted to calculate the 7-working-day milestone.
- Determine whether the application for termination of the tax identification number must be submitted directly or through the integrated mechanism.
- Record the 45-day mark separately according to the calendar date, do not convert it to 45 working days.
- Determine the date of full debt settlement to calculate the 5-working-day deadline for submitting dissolution registration documents.
- Monitor the tax authorities' response before concluding that the business has completed all procedures.
From a business perspective, companies should review their tax obligations and accounting records in parallel with handling accounts receivable. Early preparation helps reduce the risk of delays due to missing documents, incomplete tax obligations, or incorrect deadlines.
Conclusion regarding the timeframe for business dissolution.
The timeframe for dissolving a business includes several milestones related to both the dissolution registration procedure and tax procedures. The 7-day mark is calculated from the date the resolution or decision to dissolve is passed; the 45-day mark is calculated in days; and the 5-day mark in the final stage is calculated from the date all debts are settled.
Businesses need to compare each deadline with actual events and currently effective regulations, paying particular attention to Decree 296/2026/ND-CP regarding dissolution registration documents. Accurately tracking business dissolution deadlines helps avoid overlooking obligations, misunderstanding timelines, and prolonging the legal completion process.
References
- Source of information: Vietnamese Law – 7 Important Timelines Businesses Need to Remember When Dissolving or Ceasing Operations (07/09/2026).
- The legal documents used in this article are:
- Law on Enterprises 2020 – Law No. 59/2020/QH14
- Decree 168/2025/ND-CP on business registration
- Decree 296/2026/ND-CP amends Decree 168/2025/ND-CP.
- Decree 252/2026/ND-CP
- Circular 90/2026/TT-BTC on tax registration
Editor's note: This article is compiled in accordance with regulations and sources verified as of September 8, 2026. When applying it to a specific case, businesses should compare the currently effective regulations with their actual situation.
Professional license: CPA Vietnam Auditors
Experience: Over 30 years of experience in Accounting, Auditing, and Financial Consulting.




